Car Wash, Gas Station, and Self-Storage Cost Segregation
Why qualifying fuel outlets and express car wash shells drop from 39-year real estate into 15-year bonus-eligible MACRS, and how self-storage studies separate 15-year sitework and 5-year unit tech from 39-year shells.
Matthew Gigantelli
Lead Cost Seg Engineer · ASCSP M009-25
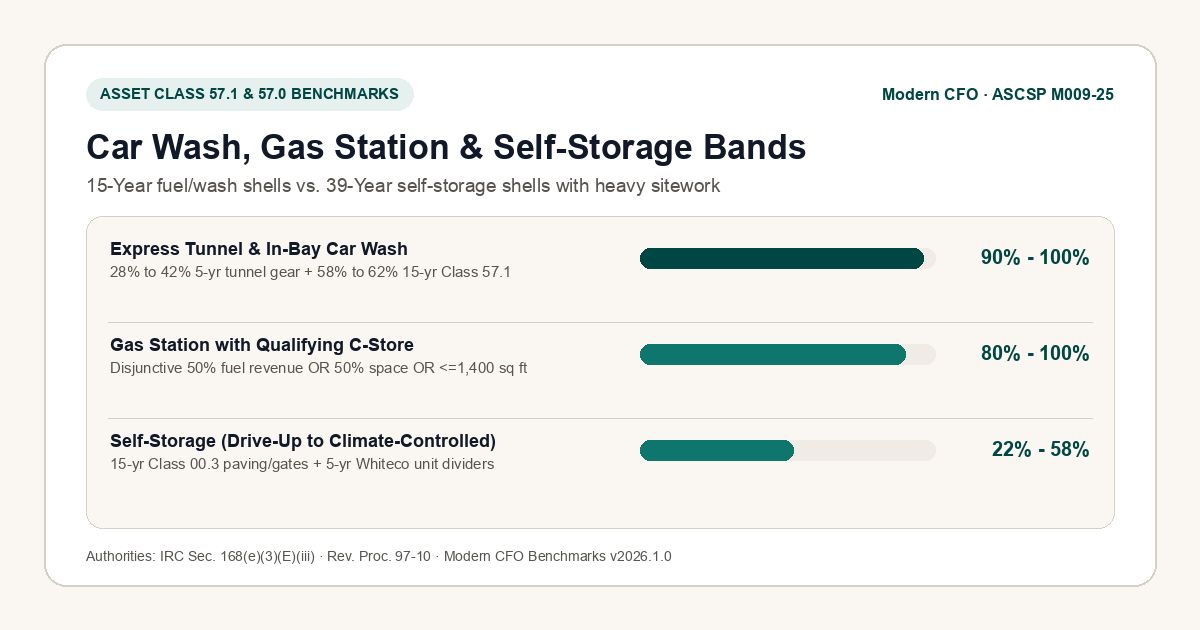
Under IRC Section 168(e)(3)(E)(iii) and Rev. Proc. 87-56 Asset Class 57.1, qualifying fuel outlets and car wash buildings earn a 15-year GDS recovery period (20-year ADS) on the building shell itself! Under the Modern CFO Cost Segregation Allocation Benchmarks (v2026.1.0, CC BY 4.0), express car washes reach 90% to 100% accelerated basis and C-store gas stations reach 80% to 100%. Self-storage shells remain 39-year property, yet 15-year sitework and 5-year unit partitions push accelerated allocations to 22% to 58%. Eligible assets acquired and placed in service after January 19, 2025 receive 100% bonus depreciation under P.L. 119-21.
Interactive Car Wash, Gas Station & Self-Storage Estimator
Model Year-1 accelerated depreciation on depreciable basis excluding land using Modern CFO v2026.1.0 midpoint bands and enacted P.L. 119-21 bonus rates.
1. Allocation Benchmarks: Car Washes, Gas Stations, and Self-Storage
Investors often group express car washes and convenience-store fuel stations alongside self-storage properties as high-cash-flow roadside real estate. Under the Internal Revenue Code, however, their structural building shells obey completely different MACRS recovery rules.
Qualifying fuel outlets and car wash buildings earn a statutory 15-year GDS recovery period (20-year ADS) on the building structure itself under Rev. Proc. 87-56 Asset Class 57.1, making up to 100% of depreciable basis eligible for bonus depreciation. Self-storage structural shells remain 39-year nonresidential real property, deriving their accelerated deductions from expansive 15-year site paving and security fencing plus 5-year modular unit systems.
| Specialty Property Subtype (Modern CFO Benchmarks v2026.1.0) | 5-Year (Class 57.0) | 15-Year (57.1 / 00.3) | Total Accelerated | 39-Year Shell |
|---|---|---|---|---|
| Gas Station (Fuel Only Canopy & Kiosk) | 32% to 42% | 58% to 68% | 100% | 0% |
| Gas Station with Convenience Store (C-Store) | 27% to 34% | 53% to 66% | 80% to 100% | 0% to 20% |
| Car Wash (Express Tunnel or Automatic In-Bay) | 28% to 42% | 58% to 62% | 90% to 100% | 0% to 10% |
| Self-Storage: Basic Single-Story Drive-Up | 12% to 24% | 20% to 34% | 32% to 58% | 42% to 68% |
| Self-Storage: Economy or Industrial Conversion | 10% to 18% | 18% to 28% | 28% to 46% | 54% to 72% |
| Self-Storage: Standard Mixed (Drive-Up + Interior Units) | 16% to 28% | 10% to 14% | 26% to 42% | 58% to 74% |
| Self-Storage: Premium Multi-Story Climate-Controlled | 14% to 26% | 8% to 12% | 22% to 38% | 62% to 78% |
Source: Modern CFO Cost Segregation Allocation Benchmarks (v2026.1.0), expert-maintained planning allocation bands expressed as percentages of depreciable basis excluding land.
2. Gas Stations & C-Stores: The Disjunctive IRC Section 168(e)(3)(E)(iii) Tests
Under IRC Section 168(e)(3)(E)(iii), any Section 1250 building qualifying as a retail motor fuels outlet is statutory 15-year property (20-year ADS) whether owner-operated or leased to a dealer. Because its MACRS recovery period is 20 years or less, the entire C-store building shell qualifies for 100% federal bonus depreciation when acquired and placed in service after January 19, 2025!
A widespread CPA misconception is assuming a C-store must satisfy both revenue and floor-space thresholds simultaneously. Under IRS Publication 946 and Rev. Proc. 97-10, the tests are disjunctive (OR, not AND). A C-store building qualifies for 15-year Asset Class 57.1 recovery if it passes any one of three bright-line tests.
- The 50% Gross Revenue Test. At least 50 percent of gross property revenues come from retail petroleum sales (excluding consumer excise taxes where applicable), OR
- The 50% Floor-Space Test. At least 50 percent of building floor space (including supporting restrooms and storage plus walk-in coolers) is devoted to marketing petroleum products. Under the IRS Retail Industry ATG and Rev. Proc. 2025-23, attached car-wash bays and lube bays plus restaurant seating are excluded from the petroleum-marketing numerator, OR
- The 1,400 Square-Foot Kiosk Exception. The C-store building measures 1,400 square feet or less, qualifying automatically as a 15-year retail motor fuels outlet without testing revenue or floor space!
Even inside a qualifying 15-year C-store, an engineering study still segregates 27% to 34% of cost into 5-year Asset Class 57.0 personal property. Qualifying 5-year assets include fuel dispensers and submerged turbine pumps alongside removable underground storage tanks, Veeder-Root tank monitors, walk-in beverage coolers, food-service gear, POS registers, plus branded LED canopy fascia. That 5-year bucket accelerates state depreciation in bonus-decoupled states and keeps bonus depreciation intact even under a Section 163(j) interest election.
3. Express Tunnel & In-Bay Car Washes: Why 90% to 100% Accelerates
Standalone express tunnel and automatic in-bay car washes are among the highest-performing tax assets in commercial real estate. Look directly at the text of Rev. Proc. 87-56 Asset Class 57.1. The 15-year class explicitly covers Section 1250 service station buildings and car wash buildings alongside related land improvements.
Because the wash tunnel enclosure itself is a 15-year Asset Class 57.1 car wash structure, both the tunnel shell and surrounding stacking lanes plus vacuum canopies, trench pits, alongside signage earn 15-year recovery (58% to 62% of basis). Only detached corporate offices or unrelated retail suites (0% to 10% of basis) remain in 39-year real property.
Inside the tunnel and mechanical room, an engineering study isolates 28% to 42% of project cost into 5-year Asset Class 57.0 machinery and process utilities under Scott Paper Co. (74 T.C. 137). Qualifying 5-year items include conveyor tracks and wrap brushes alongside chemical arches, drying blowers, reverse-osmosis skids, underground water reclamation tanks, central vacuum turbines, license-plate pay gates, plus dedicated 480V process panels.
4. Self-Storage Engineering: 39-Year Shells vs. Drive-Up Sitework & Unit Tech
Self-storage facilities do NOT qualify for Asset Class 57.1. Consequently, concrete slab foundations and structural steel framing alongside standing-seam metal roofs, elevator shafts, general building comfort HVAC, plus permanent exterior perimeter roll-up doors stay in 39-year IRC Section 1250 real property.
Yet Modern CFO benchmarks still show 32% to 58% accelerated allocations on Basic Single-Story Drive-Up properties and 22% to 38% on Multi-Story Climate-Controlled facilities. Drive-up storage achieves higher percentages because horizontal acreage goes into 15-year Asset Class 00.3 site improvements (20% to 34%). Those 15-year site assets include asphalt and concrete RV drive aisles alongside perimeter fencing, motorized keypad slide gates, pole-mounted LED lighting, retaining walls, plus stormwater detention ponds.
Inside multi-story and mixed facilities, 5-year Asset Class 57.0 personal property drives 10% to 28% of basis. Under Whiteco Industries (65 T.C. 664), non-load-bearing corrugated unit-divider walls and modular hallway systems fastened with self-tapping screws can be reconfigured to resize units without damaging the structural frame. Smart Bluetooth cylinder locks and access keypads alongside 4K CCTV security networks, leasing-office millwork, plus dedicated specialty dehumidification units meeting 26 CFR 1.48-1(e)(2) also take 5-year recovery.
| Specialty Component Across Car Wash, Fuel & Storage | MACRS Class & GDS / ADS | Primary Authority |
|---|---|---|
| Fuel dispensers, submerged pumps, removable USTs, POS consoles & C-store walk-in coolers | 5-Year (57.0) / 9-Yr ADS | Rev. Proc. 87-56 Class 57.0; IRS Retail ATG |
| Car wash conveyors, arches, blowers, RO/water reclaim skids, vacuums, LPR gates & 480V process feeds | 5-Year (57.0) / 9-Yr ADS | Rev. Proc. 87-56 Class 57.0; Scott Paper, 74 T.C. 137 |
| Self-storage removable corrugated unit dividers, smart locks, CCTV cameras & specialty dehumidifiers | 5-Year (57.0) / 9-Yr ADS | Whiteco Industries, 65 T.C. 664; 26 CFR 1.48-1(e)(2) |
| Qualifying C-store building shell (>=50% fuel revenue OR >=50% fuel space OR <=1,400 sq ft) & fuel canopy | 15-Year (57.1) / 20-Yr ADS | IRC Section 168(e)(3)(E)(iii); Rev. Proc. 97-10 |
| Express tunnel & in-bay car wash building enclosure, concrete reclaim pits, vacuum canopies & lanes | 15-Year (57.1) / 20-Yr ADS | Rev. Proc. 87-56 Asset Class 57.1 |
| Self-storage asphalt/concrete drive aisles, security fencing, keypad slide gates, pole lighting & ponds | 15-Year (00.3) / 20-Yr ADS | Rev. Proc. 87-56 Asset Class 00.3 |
| Self-storage structural steel frame, slabs, roof, exterior roll-up doors & non-qualifying C-store shells | 39-Year Real / 40-Yr ADS | IRC Section 1250; IRC Section 168(c) |
Many gas station and car wash owners alongside self-storage operators discover years after closing that their prior CPA booked a qualifying 15-year Asset Class 57.1 building or 15-year drive-up storage paving to 39-year straight-line depreciation. Under Rev. Proc. 2025-23 (the successor procedure to Rev. Proc. 2011-14), filing Form 3115 (Designated Change Number 7) fixes this without amending prior returns. The owner claims 100% of missed prior depreciation and applicable bonus in a single current-year IRC Section 481(a) catch-up deduction. Modern CFO engineering study fees run $1,200 to $2,500 for small residential properties and $2,500 to $6,000 for standard commercial sites (up to $6,000 to $12,000 for large multi-site portfolios).
5. Frequently Asked Questions
Does a convenience store gas station have to pass both the 50% revenue and 50% floor-space tests?
No. Under IRC Section 168(e)(3)(E)(iii) and IRS Publication 946 plus Rev. Proc. 97-10, the tests are disjunctive (OR). A C-store building qualifies for 15-year Asset Class 57.1 recovery if petroleum sales provide 50% or more of gross revenues, OR petroleum marketing occupies 50% or more of floor space, OR the C-store building is 1,400 square feet or less.
Why do express tunnel car washes reach 90% to 100% bonus-eligible depreciation?
Rev. Proc. 87-56 Asset Class 57.1 explicitly classifies car wash buildings and related land improvements as 15-year MACRS property (58% to 62% of basis). Conveyor tracks and brushes alongside blowers, RO/water reclaim skids, plus vacuums classify as 5-year Asset Class 57.0 personal property (28% to 42% of basis). Both 5-year and 15-year buckets qualify for 100% bonus depreciation when acquired and placed in service after January 19, 2025.
Why does drive-up self-storage segregate a higher percentage than multi-story climate-controlled storage?
Self-storage structural shells stay in 39-year real property. Single-story drive-up facilities allocate 20% to 34% of basis into 15-year Asset Class 00.3 site paving and fencing with gates and lighting. Adding 12% to 24% in 5-year unit dividers and security yields 32% to 58% total accelerated basis, versus 22% to 38% for multi-story climate-controlled shells.
Can I reclassify a C-store or car wash placed in service in an earlier year without amending returns?
Yes. Filing Form 3115 under Designated Change Number 7 (Rev. Proc. 2025-23) reclassifies a 39-year C-store or car wash into 15-year Asset Class 57.1 and 5-year Asset Class 57.0, deducting all missed prior depreciation in the current tax year via an IRC Section 481(a) adjustment.
Estimate Your Car Wash, Gas Station, or Self-Storage Tax Shield
Run a free instant cost segregation estimate for any specialty property subtype, or inspect our companion guides on acquisition contract cutoffs and clinical real estate.